US Estate Tax for Singapore Investors: What You Need to Know
  • Post author:

Introduction

Investing in the US stock market has become increasingly accessible to Singaporeans. From established technology companies such as Apple and Microsoft to growth-oriented businesses such as NVIDIA, investors can build portfolios across a wide range of industries through international brokerage platforms.

However, investing overseas involves more than evaluating stock prices and potential returns. Singapore investors who own US shares directly should also understand the potential estate tax implications of their investments.

Although Singapore abolished estate duty in 2008, the United States continues to impose estate tax on certain US-situated assets owned by non-US citizens who are not domiciled in the country. Depending on the circumstances, this tax can reach 40% and may significantly reduce the wealth eventually passed on to family members.

Understanding these rules and reviewing your investment structure can help you make more informed decisions about long-term wealth preservation and succession planning.

1. What Is US Estate Tax and Why Does It Matter to Singaporeans?

US estate tax is a tax imposed on the transfer of a deceased person’s taxable estate. For individuals who are neither US citizens nor domiciled in the United States, the rules generally focus on assets classified as situated in the US.

These assets may include:

  • Shares issued by US-incorporated companies.
  • US real estate.
  • Certain other US-situated property and securities.

Importantly, holding US shares through a Singapore-based brokerage account does not, by itself, remove the potential estate tax exposure. The legal classification of the underlying investment matters more than the location of the brokerage platform.

For many non-US investors, the applicable filing threshold is US$60,000 in US-situated assets. If the relevant threshold is exceeded, an estate tax return may be required, and tax may be payable depending on the estate’s circumstances and applicable deductions or credits.

US federal estate tax rates can reach 40%, making this an important consideration for investors with substantial US stock holdings.

2. How Much Could US Estate Tax Affect Your Portfolio?

Consider a hypothetical Singapore investor who owns US stocks worth US$1 million at the time of death.

Under the general rules for non-US citizens who are not domiciled in the United States, the estate may have only a limited exemption or credit available compared with the much larger exemption generally available to qualifying US citizens and residents.

Consequently, a substantial portion of the portfolio could be exposed to US estate tax.

It is important to distinguish the value potentially subject to tax from the final tax payable. The US$60,000 threshold is not a universal flat deduction from which the final liability can simply be calculated at 40%. The actual tax depends on the applicable graduated rates, available credits, allowable deductions and the investor’s circumstances.

Nevertheless, the example highlights why investors should review their exposure before their portfolio grows significantly.

3. Five Estate Planning Considerations for Singapore Investors

Strategy 1: Review Your Portfolio and Fund Domicile

One approach is to review how your US market exposure is held.

Investors may consider whether to hold individual US shares directly or obtain broader US market exposure through funds domiciled outside the United States.

For example, certain Ireland-domiciled exchange-traded funds (ETFs) provide exposure to US indices without being US-domiciled funds themselves. The domicile of a fund, rather than simply the exchange on which it trades, is an important factor when assessing estate tax treatment.

Investors should also consider diversification, fund expenses, dividend withholding tax, currency exposure and trading costs before changing their portfolios.

Strategy 2: Explore Insurance-Based Investment Structures

Some insurance-based investment products provide exposure to international markets through an insurance policy rather than direct personal ownership of the underlying investments.

Depending on the policy terms, ownership arrangements and applicable tax rules, such structures may have different estate tax implications from directly held US shares.

However, these products vary considerably in cost, flexibility, investment options and benefits. Investors should carefully review the policy structure and obtain appropriate professional advice rather than assuming that every investment-linked insurance policy eliminates US estate tax exposure.

Strategy 3: Assess Whether a Holding Company Is Appropriate

Investors with larger portfolios may explore holding investments through a company incorporated outside the United States, such as a Singapore company.

Under an appropriately structured arrangement, the individual may own shares in the holding company rather than personally owning the underlying US investments. This can change the estate tax analysis, but it does not automatically eliminate all tax exposure.

Company incorporation, accounting, regulatory compliance, potential taxation on distributions or share disposals, and the treatment of the company’s shares must all be considered.

The additional administrative burden and cost mean that this approach may not be suitable for every investor.

Strategy 4: Consider Trust-Based Estate Planning

A trust may help investors organise how wealth is managed and distributed to beneficiaries over time.

Depending on the structure, a trust can establish arrangements for asset management, succession and the interests of future generations. However, transferring assets into a trust does not automatically remove them from a taxable estate.

The legal ownership, trust terms, timing of transfers, retained powers and relevant tax rules can all affect the outcome.

Because trust arrangements can be complex and costly, investors should seek advice from qualified legal and cross-border tax professionals before proceeding.

Strategy 5: Plan for Potential Tax Liabilities With Life Insurance

Life insurance can also be considered as part of a broader succession plan.

For investors who retain significant US-situated assets, an appropriately designed policy may provide funds that beneficiaries can use to meet estate-related expenses and potential tax liabilities.

This can help reduce the need to sell investments under unfavourable market conditions simply to obtain cash.

However, the policy’s ownership, beneficiary arrangements, coverage amount and tax treatment must be assessed carefully. Life insurance should complement a comprehensive estate plan rather than serve as a substitute for reviewing the underlying tax exposure.

4. Estate Administration: What Happens When an Investor Passes Away?

Estate planning involves more than estimating a possible tax bill. The administration of an estate containing US assets can also create procedural challenges for beneficiaries.

Where required, the executor may need to submit IRS Form 706-NA, the US estate tax return for nonresident individuals who are not US citizens. The general filing deadline is nine months after death, although an extension may be available.

The executor may also need to provide supporting documentation and address outstanding tax liabilities before the relevant US assets can be transferred.

Depending on the custodian and the circumstances, the process can involve additional paperwork, professional fees and delays in distributing assets to beneficiaries.

Maintaining an accurate record of brokerage accounts, investment holdings and relevant estate planning documents can help family members and executors manage these responsibilities more effectively.

5. Make US Estate Tax Part of Your Long-Term Wealth Plan

Investing in US equities can provide valuable access to global businesses and growth opportunities. However, investors should evaluate not only how their portfolios perform during their lifetime but also how their assets may be treated when transferred to the next generation.

Singapore investors can start by identifying their US-situated holdings, checking the domicile of their funds and reviewing the ownership arrangements for their investments.

More complex options involving insurance, companies or trusts should be evaluated against the investor’s objectives, portfolio size, costs and wider tax circumstances.

There is no single structure that is appropriate for everyone. A well-considered approach should balance investment objectives, tax considerations, administrative complexity and the practical needs of beneficiaries.

Protecting wealth is not just about growing your investments. It is also about planning how that wealth can be managed and transferred in the future.

Disclaimer: This article is for general educational purposes only and does not constitute tax, legal or investment advice. US estate tax rules depend on individual circumstances, asset classification and applicable law. Consult qualified cross-border tax and legal professionals before making decisions about your investments or estate structure.

Kenny Loh is a distinguished Wealth Advisory Director with a specialisation in holistic investment planning and estate management. He excels in assisting clients to grow their investment capital and establish passive income streams for retirement. Kenny also facilitates tax-efficient portfolio transfers to beneficiaries, ensuring capital appreciation through risk mitigation approaches and optimised wealth transfer through strategic asset structuring.

In addition to his advisory role, Kenny is an esteemed SGX Academy trainer specializing in S-REIT investing and regularly shares his insights on MoneyFM 89.3. He holds the titles of Certified Estate & Legacy Planning Consultant and CERTIFIED FINANCIAL PLANNER (CFP).

With over a decade of experience in holistic estate planning, Kenny employs a unique “3-in-1 Will, LPA, and Standby Trust” solution to address clients’ social considerations, legal obligations, emotional needs, and family harmony. He holds double master’s degrees in Business Administration and Electrical Engineering, and is an Associate Estate Planning Practitioner (AEPP), a designation jointly awarded by The Society of Will Writers & Estate Planning Practitioners (SWWEPP) of the United Kingdom and Estate Planning Practitioner Limited (EPPL), the accreditation body for Asia.

For enquiries email: kennyloh@fapl.sg

You can join his Telegram channel #REITirement – SREIT Singapore REIT Market Update and Retirement related news. https://t.me/REITirement

Continue ReadingUS Estate Tax for Singapore Investors: What You Need to Know

Kenny Loh Shares HOLD? When REIT Prices Fall, Are Dividends Enough Reason to Hold? — Ep 18

  • Post author:

Watch the full video here: https://youtu.be/CL80Zb3y5ns?si=BZ6R7RJKa3tPbUmF

In this episode of The One Good Chat Podcast, Joey and the team sit down with Kenny Loh (founder of REITsavvy) to discuss building sustainable passive income and protecting family wealth. Kenny covers his shift from engineering to finance, Singapore REIT strategies—including dividend sustainability and optimal entry timing—and critical estate planning tools like wills, trusts, and Lasting Power of Attorney (LPA).

Check out Kenny Loh, Founder of REITsavvy here:   @kennylohfinancialwisdom  

Check out Kenny’s upcoming estate planning seminar here: https://www.eventbrite.sg/e/guarding-…


Kenny Loh is a distinguished Wealth Advisory Director with a specialisation in holistic investment planning and estate management. He excels in assisting clients to grow their investment capital and establish passive income streams for retirement. Kenny also facilitates tax-efficient portfolio transfers to beneficiaries, ensuring capital appreciation through risk mitigation approaches and optimised wealth transfer through strategic asset structuring.

In addition to his advisory role, Kenny is an esteemed SGX Academy trainer specializing in S-REIT investing and regularly shares his insights on MoneyFM 89.3. He holds the titles of Certified Estate & Legacy Planning Consultant and CERTIFIED FINANCIAL PLANNER (CFP).

With over a decade of experience in holistic estate planning, Kenny employs a unique “3-in-1 Will, LPA, and Standby Trust” solution to address clients’ social considerations, legal obligations, emotional needs, and family harmony. He holds double master’s degrees in Business Administration and Electrical Engineering, and is an Associate Estate Planning Practitioner (AEPP), a designation jointly awarded by The Society of Will Writers & Estate Planning Practitioners (SWWEPP) of the United Kingdom and Estate Planning Practitioner Limited (EPPL), the accreditation body for Asia.

For enquiries email: kennyloh@fapl.sg

You can join his Telegram channel #REITirement – SREIT Singapore REIT Market Update and Retirement related news. https://t.me/REITirement
Continue ReadingKenny Loh Shares HOLD? When REIT Prices Fall, Are Dividends Enough Reason to Hold? — Ep 18

Do You Need a Trust?

  • Post author:

When it comes to legacy and wealth planning, “setting up a trust” is often treated as the ultimate status symbol. We see it in movies, read about it in articles covering ultra-high-net-worth families, and hear wealth managers mention it as the gold standard of asset protection.

But let’s strip away the prestige and look at the reality. A trust is a powerful legal structure, but it is also an ongoing operational commitment that involves setup fees, annual administrative maintenance, and a transfer of legal ownership.

The honest truth? Not everyone needs a trust. For many people, a robust Will, a Lasting Power of Attorney (LPA), and proper insurance nominations are more than enough.

So, how do you know if you are crossing the line from needing a basic estate plan to needing a full structural trust? Instead of looking at complex legal definitions, let’s look at your actual life.

Ask yourself the following questions to see which scenario fits your reality.

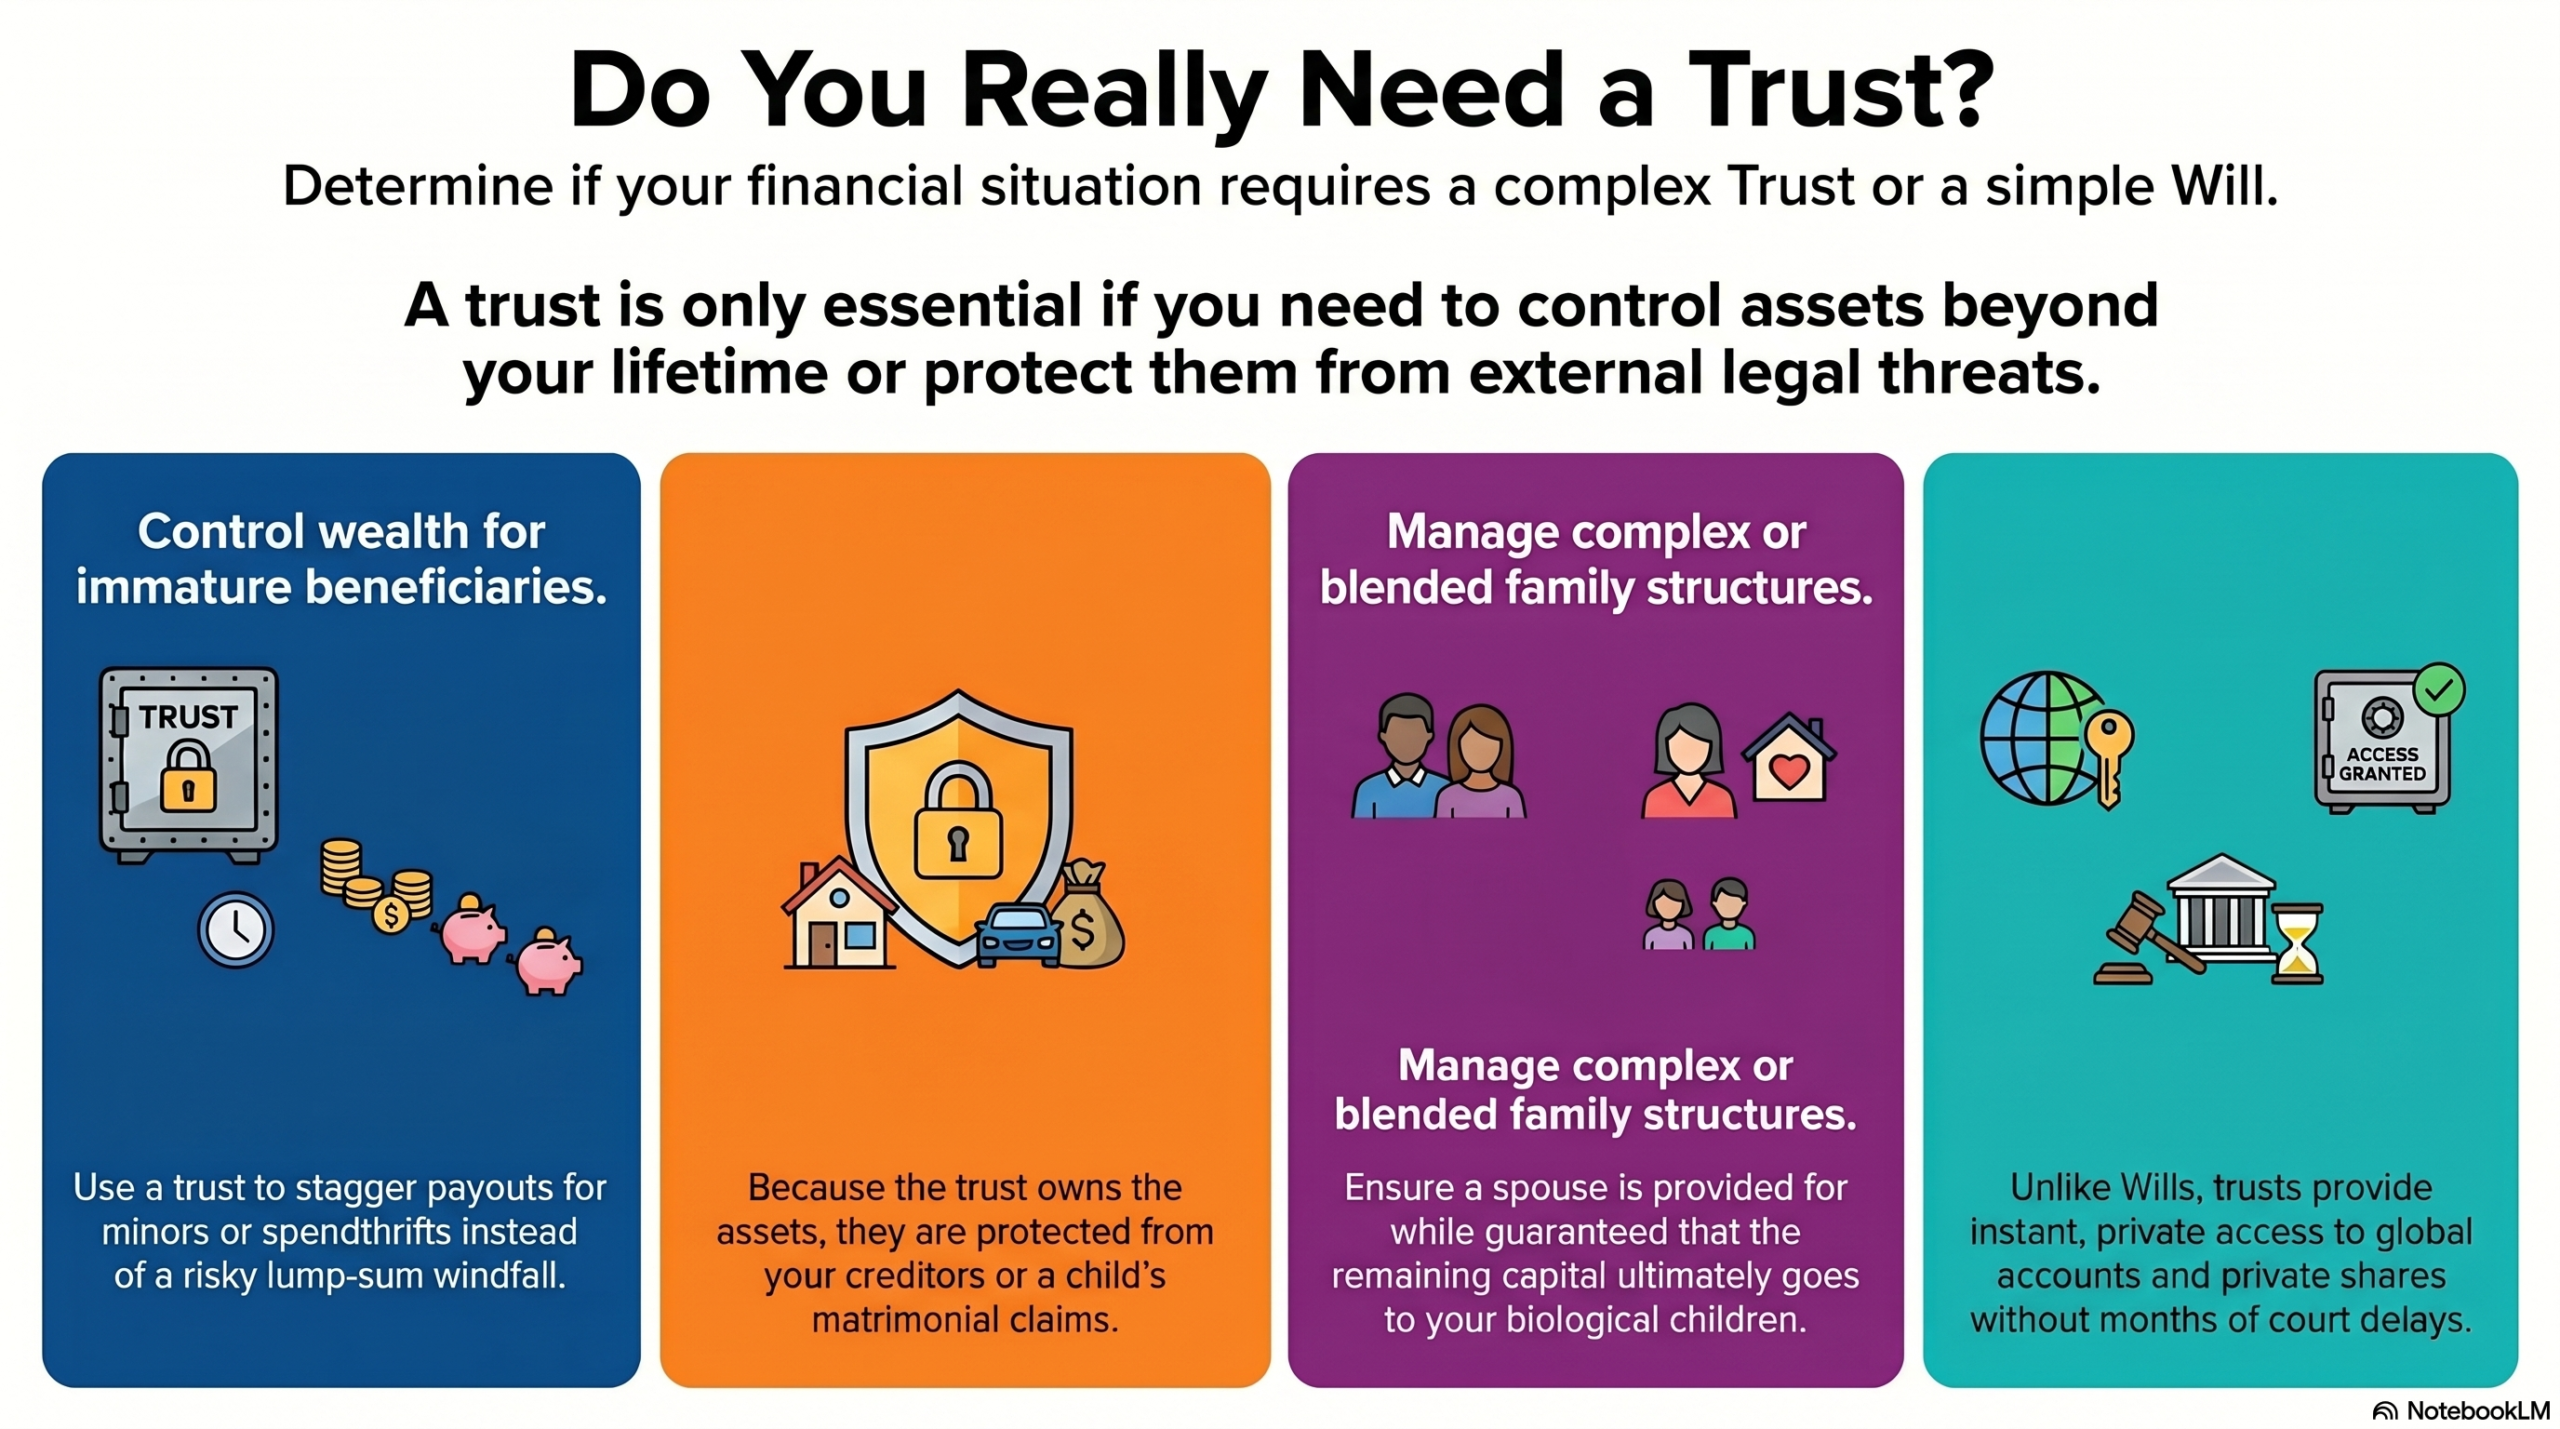
Scenario 1: The Maturity Question

“If something happens to me tomorrow, will my beneficiaries spend their inheritance wisely?”

Imagine you leave behind a significant life insurance payout or a large cash portfolio.

  • If your children are minors (under 21): Legally, they cannot receive large sums of money directly. The court will appoint a guardian to manage it, or the funds will be tied up until they hit adulthood.
  • If your children are in their early 20s: If a 22-year-old suddenly receives a $1 million windfall, will they invest it in their future, or will it disappear into high-end cars, lifestyle inflation, and poor business ventures?

How a Trust Answers This: If you find yourself worrying about the financial maturity of your loved ones, a trust is highly relevant. A trust allows you to act as a “ghost pilot.” Instead of a lump-sum payout, the corporate trustee can distribute a fixed monthly allowance for living expenses, pay universities directly for tuition, or unlock specific percentages of the wealth only when your children hit maturity milestones (e.g., 25, 30, and 35 years old).

.

Scenario 2: The Asset Protection Question

“Am I exposed to professional lawsuits, or do I worry about family divorces eroding our wealth?”

Think about your profession and the future relationships of your heirs.

  • Are you a business owner, a medical specialist, or a corporate director where a personal or professional lawsuit could target your personal balance sheet?
  • If you pass your wealth down to your child, and their marriage unfortunately ends in a messy divorce years later, are you comfortable knowing that a portion of your family’s hard-earned wealth could be claimed as a matrimonial asset by an ex-spouse?

How a Trust Answers This: When you put assets into an irrevocable trust, you technically transfer the legal ownership of those assets to the trustee. Because you no longer legally “own” the wealth, future creditors, lawsuits, or bankruptcy claims against you cannot touch it. Similarly, because the assets are held safely within the trust wrapper for your child rather than being owned by them outright, it adds a formidable layer of defense against matrimonial asset division during a divorce.

.

Scenario 3: The Complex Family Dynamics Question

“Does my family structure look different from a traditional, single-nucleus model?”

Standard estate laws and default Wills are designed for traditional family structures.

  • Are you part of a blended family where there are children from a previous marriage as well as a current marriage?
  • Do you want to ensure your current spouse is financially taken care of for the rest of their life, but guarantee that the remaining capital ultimately goes to your biological children rather than a future stepfather or stepmother?
  • Do you have a family member with special needs who will require lifelong financial care long after you are gone?

How a Trust Answers This: A Will can easily be contested, and once an asset is willed directly to a spouse, you lose all control over what they do with it next. A trust solves this beautifully through a “Life Interest” clause. You can structure the trust so that your spouse receives all the investment income or has the right to live in the family property for life. However, upon their passing, the trust rules dictate that the core assets automatically route to your children—ensuring everyone you love is protected exactly how you intended.

.

Scenario 4: The Asset Complexity Question

“Does my wealth cross international borders, or do I own private company shares?”

Look closely at what you actually own.

  • Do you own real estate in multiple countries, global equity portfolios, or shares in a private limited family business?
  • Are you aware of how long it takes for a court to grant a Grant of Probate to execute a standard Will when cross-border assets are involved? (Hint: It can take many months, sometimes years, during which your family’s access to funds is completely frozen).

How a Trust Answers This: Unlike a Will, which only activates after you pass away and must go through a lengthy public court validation process (probate), a trust is alive right now. Because the trust already owns the global accounts or company shares, the transition of management upon your passing is instantaneous and completely private. There is no probate, no frozen bank accounts, and no operational downtime for your family business.

The Verdict: Do You Actually Need a Trust?

If you answered “No” to all the questions above—meaning your children are mature adults, you have no high-risk liability exposure, your family structure is straightforward, and your wealth is entirely local and liquid—you likely do not need a trust right now. A pristine Will and an updated Lasting Power of Attorney are your best moves.

However, if you answered “Yes” to even one of these questions, a trust should shift from a distant luxury to an active conversation in your wealth strategy.

Remember, a trust is only as good as the overarching estate strategy it supports. Before you jump into picking a trustee or moving your funds, it is vital to map out your entire asset ecosystem and define your true family objectives first.

Unsure where your estate stands? Don’t try to self-diagnose your legacy needs. Schedule an estate planning consultation today to evaluate your asset profile, review your family goals, and discover if a trust is the right vehicle for your future.


Kenny Loh is a distinguished Wealth Advisory Director (RNF# LKK300389588 Representing Financial Alliance) with a specialization in holistic investment planning and estate management. He excels in assisting clients to grow their investment capital and establish passive income streams for retirement. Kenny also facilitates tax-efficient portfolio transfers to beneficiaries, ensuring tax-efficient capital appreciation through risk mitigation approaches and optimized wealth transfer through strategic asset structuring.

In addition to his advisory role, Kenny is an esteemed SGX Academy trainer specializing in S-REIT investing and regularly shares his insights on MoneyFM 89.3. He holds the titles of Certified Estate & Legacy Planning Consultant and CERTIFIED FINANCIAL PLANNER (CFP).

With over a decade of experience in holistic estate planning, Kenny employs a unique “3-in-1 Will, LPA, and Standby Trust” solution to address clients’ social considerations, legal obligations, emotional needs, and family harmony. He holds double master’s degrees in Business Administration and Electrical Engineering, and is an Associate Estate Planning Practitioner (AEPP), a designation jointly awarded by The Society of Will Writers & Estate Planning Practitioners (SWWEPP) of the United Kingdom and Estate Planning Practitioner Limited (EPPL), the accreditation body for Asia.

Arrange for a non-obligatory one-to-one free consultation here!

You can join his Telegram channel #REITirement – SREIT Singapore REIT Market Update and Retirement related news. https://t.me/REITirement
If you need any financial advice, please contact kennyloh@fapl.sg

Continue ReadingDo You Need a Trust?