Invest in Orchard Road, Singapore, with S-REITs!

  • Post author:

Orchard Road is home to familiar names such as Takashimaya, Paragon, Plaza Singapura, 313@Somerset. But with S-REITs, you can invest in a part of Singapore’s largest retail district.
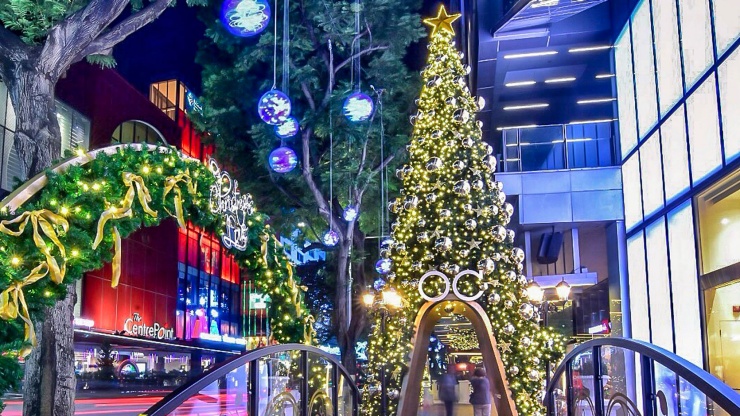
Orchard Road during the holiday season, where Christmas decorations are in full swing. Photo: visitsingapore

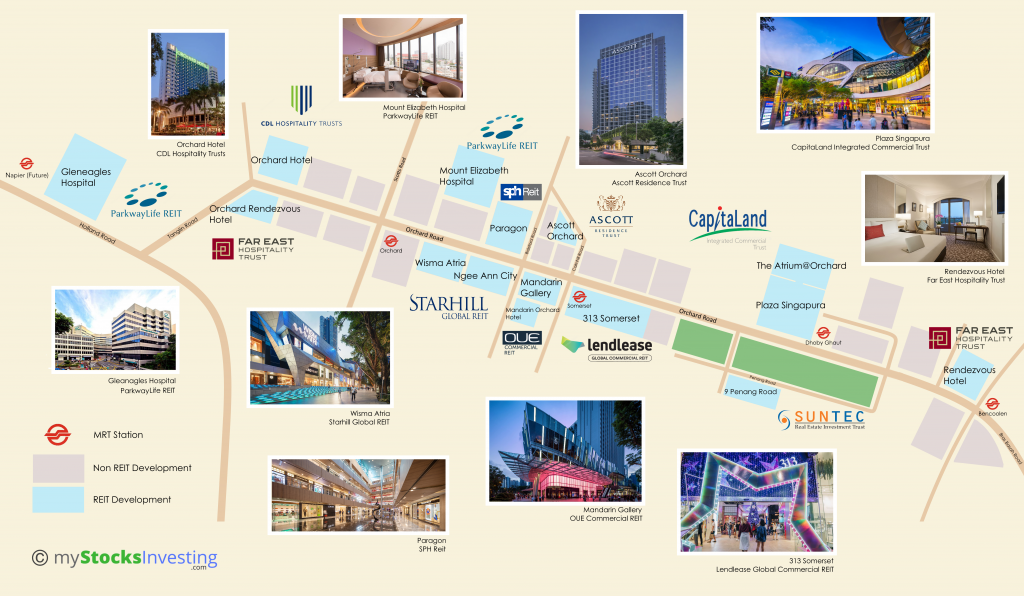
Retail is not the only REIT sector along Orchard Road. Despite mostly having a Retail REIT presence, there are also several other REIT sectors, such as hospitality and office REITs in the vicinity. Below are some of the REITs found in Orchard Road, with a handy diagram on where they are located within the shopping district. Property valuation figures are accessed via the REIT’s website as of 5th Februrary 2021.


Retail/Integrated Developments

Located next to Dhoby Ghaut MRT, Capitaland Integrated Commercial Trust, Singapore’s largest REIT by market capitalisation, has portfolios consisting of both The Atrium@Orchard and Plaza Singapura along Orchard Road. With large tenants such as Spotlight and Golden Village, both properties have a total property valuation of S$2.04 billion.

Starhill Global’s portfolio includes Wisma Atria and Ngee Ann City along Orchard Road. Both are integrated Retail and Office developments, including anchor tenants such as Takashimaya Department Store. Located next to Orchard MRT, they have a combined property valuation of S$2.062 billion.

Located right above Somerset MRT, 313@Somerset is Lendlease Global Commercial REIT’s presence in Orchard Road. 313@Somerset includes many fashion tenants such Love Bonito, ZARA, FOREVER 21, Cotton On and The Editor’s Market etc. It has a property valuation of S$1.008 billion.

OUE Commercial REIT has 2 properties along Orchard Road, namely Mandarin Gallery and Mandarin Orchard Hotel. Mandarin Gallery specialises in high-end retail with many brands such as Bathing Ape and HUGO BOSS, while Mandarin Orchard Hotel is an upscale hotel with 1,077 rooms. Both have a combined portfolio valuation of S$1.721 billion.

Paragon is a premier upscale mall, specialising in high end retail and fashion. Paragon also houses Paragon Medical, which hosts approximately 90 medical and dental specialist clinics and offices.


Office

The newest property included within this article, 9 Penang Road is a newly completed Grade A commercial building. The ten-storey development consists of two towers with office space across eight floors and retail space at the first level. It has a property valuation of S$276.0 million.


Hospitality

Located behind Knightsbridge Mall (or more easily known as the mall with Apple Store Orchard), Ascott Orchard is a serviced residence consisting of 220 suites comprising studios to two-bedroom units and penthouses. It has a property valuation of $413 million.

Far East Hospitality Trust’s portfolio consists of 2 hotels, Orchard Rendezvous Hotel at the western end and Rendezvous Hotel at the eastern end of Orchard Road. Combined, there are 686 guest rooms between the 2 hotels, with a property valuation of S$715.3 million.

Located opposite Orchard Rendezvous Hotel, Orchard Hotel has 656 guest rooms. Adjacent to Orchard Hotel is Claymore Connect, a small lifestyle mall. Both properties have a combined property valuation of S$466.0 million.


Healthcare

ParkwayLife REIT has 2 hospitals, one within Orchard (Mount Elizabeth Hospital) and one in the nearby Tanglin area (Gleneagles Hospital). Gleneagles Hospital consists of 257 beds while Mount Elizabeth Hospital has 345 beds. They have a combined total property valuation of S$1.143 billion.


Below is map which highlights the approximate location of each of the properties listed above, including several landmarks such as MRT stations. The map is not drawn to scale.
 

Portfolio Information is just one of the fundamentals to look at when choosing which REITs to invest in. One of which is gearing ratio (leverage ratio). Yield and lease management of REITs are also factors to consider.  For example, a property located along Orchard Road (good location) but with low occupancy rates (bad) is not necessarily good.

By investing in one of the above REITs, you will be investing in the REIT as a whole. For example, by investing in Suntec REIT, you will not just be investing in 9 Penang Road, but Suntec City Mall and Office Towers too.

In the following, using the StocksCafe REIT screener (free version), we can compare the Market Capitalisations, Yield (trailing twelve months) and Gearing Ratios for each of the REITs listed above.

Fundamental Ratios for each of the 10 REITs with properties along Orchard Road. Data taken from StocksCafe. REITs with Period Ending 31 December 2020 are updated with the latest Q4 2020 business and earning updates. Data accessed 5th February 2021.

The above table shows the 10 S-REITs, sorted by market capitalisation in descending order. For yield, the value is calculated using the trailing twelve months distribution per unit (DPU) data. Therefore it may be lower than usual due to dividend cuts brought about by the Covid-19 pandemic. Gearing is simply the percentage of total debt/total equity.

For more detailed and regularly updated information for each of the REITs, do try out and subscribe to the comprehensive StocksCafe REIT Screener. At ~$8.40 per month (current early bird promotion with a yearly subscription), get access to much more information such as occupancy rates, debt information, interest coverage ratio etc. for each REIT. You can try out the features here.
Continue ReadingInvest in Orchard Road, Singapore, with S-REITs!

Integrated Retail/Office Development REITs: How do they compare?

  • Post author:

On the 3rd November 2020, Capitaland Mall Trust began trading as Capitaland Integrated Commercial Trust (CICT), following the merger of Capitaland Mall Trust and Capitaland Commercial Trust. Following the merger, Capitaland Integrated Commercial Trust now has 24 Retail/Office/Integrated Development properties in Singapore.

Following this merger, out of the top 10 REITs in terms of market capitalisation, there are now 3 REITs in Singapore with both Retail, Office and Integrated Development properties, including Mapletree Commercial Trust and Suntec REIT. In this article, we will be comparing how these REITs stack up, using portfolio information, financial ratios, etc.

REIT Portfolio Overview

Capitaland Mall Trust recently merged with Capitaland Commercial Trust, to form Capitaland Integrated Commercial Trust. With a total of 24 properties, which include office towers in the CBD area and retail malls distributed around Singapore, CICT is the largest market capitalisation trust in Singapore, with a total portfolio valuation of S$22.4 billion.


Having a portfolio which includes VivoCity, Singapore’s largest shopping mall, and Mapletree Business City, one of the largest Integrated Developments in Singapore, Mapletree Commercial Trust is the 4th largest REIT in terms of market capitalisation as of 4th January 2021. With 5 properties located in the south of Singapore, it has a portfolio valuation of S$8.9 Billion.


With 5 properties in Australia and 4 in Singapore, Suntec REIT has a portfolio valuation of S$10.5 Billion. Properties owned by Suntec REIT include Suntec City, one of Singapore’s largest commercial developments, encompassing 5 office towers, a shopping mall and a convention centre.

Portfolio Distribution

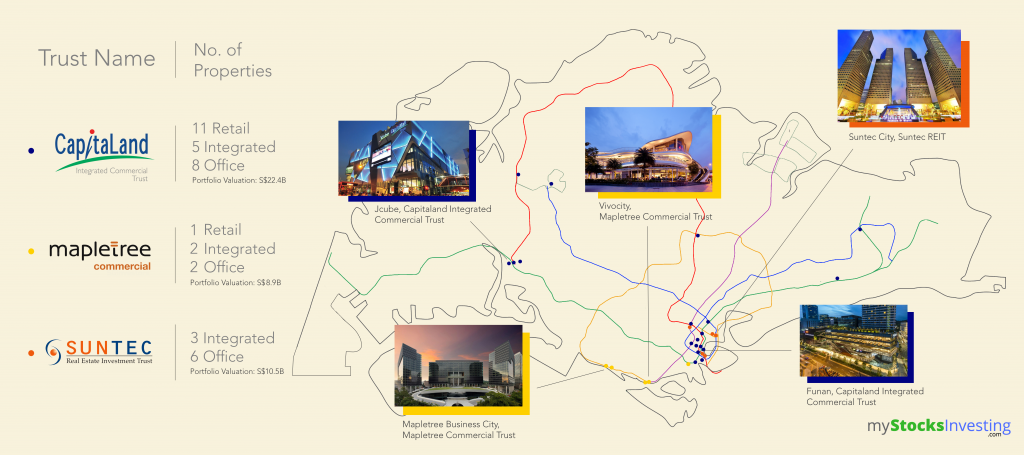
The above diagram shows the geographical distribution of each of the REIT’s portfolio locations. Some of the observations that can be drawn out include:

  • Capitaland Integrated Commercial Trust properties can be found throughout Singapore, even in heartland areas. For example, Junction 8 Shopping Centre in Bishan.
  • 4 of Mapletree Commercial Trust properties are in the Harbourfront/Alexandra precinct, close to Singapore’s downtown area, with one in the CBD area.
  • Out of these 3 REITs, Suntec REIT is the only REIT which owns overseas properties in Australia. In Singapore, all their properties are located in the CBD area.

Fundamental Ratios

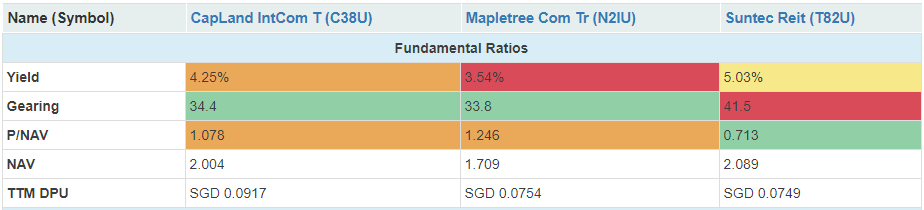
Funamental Ratio comparison between the 3 REITs. Information taken from the StocksCafe REIT screener. Values taken on 4th January 2021. Note that for CICT, values for the former Capitaland Mall Trust are shown.

Need a comprehensive S-REITs screener, complete with comparison features? Want to compare Financial Ratios of 37 other S-REITs?

Do subscribe to the StocksCafe REIT screener now! You can opt for a monthly subscription, or a yearly subscription for 10% off! For a limited time only.

The above table shows the corresponding fundamental ratios of the 3 REITs. Some observations that can be made are shown below:

  • Yield (ttm): At current prices, Mapletree Commercial Trust has the lowest yield of 3.54%. However, yield (ttm) is not a meaningful unit of measurement at the moment, due to recent dividend cuts due to the pandemic, and the switching of dividend payouts of some REITs to a semi-annual payout schedule (e.g Starhill Global REIT).
  • Gearing: Capitaland Integrated Commercial Trust and Mapletree Commercial Trust have a gearing ratio of about 34%, while Suntec REIT has a high gearing ratio of 41.5%.
  • Capitaland Integrated Commercial Trust is currently slightly overvalued, at Price/NAV of 1.078. Mapletree Commercial Trust is relatively overvalued while Suntec REIT is relatively undervalued.

Lease Management

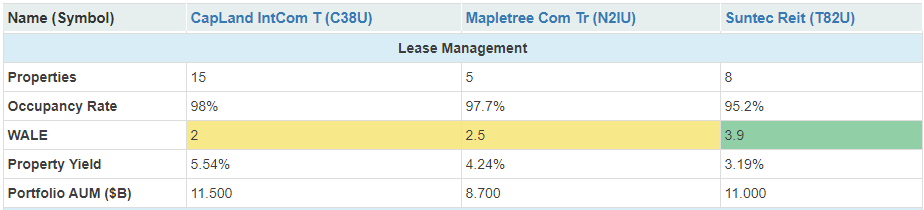
Lease Management comparison between the 3 REITs. Information taken from the StocksCafe REIT screener. Values taken on 4th January 2021. Note that for CICT, values for the former Capitaland Mall Trust are shown.

The above table shows the corresponding lease management values of the 3 REITs. Note that for CICT, values for the former Capitaland Mall Trust are shown above instead. Some observations that can be made are shown below:

  • Number of Properties: Capitaland Integrated Commercial Trust owns the most properties, with 24 properties after the merger. Suntec REIT is the only REIT here with overseas properties, namely in Australia.
  • Occupancy Rate: All 3 REITs have strong occupancy rates of above 95%, with the lowest being Suntec REIT at 95.2%.
  • Weighted Average Lease Expiry (WALE): Suntec REIT has the highest WALE value at 3.5 years.
  • Property Yield: Capitaland Integrated Commercial Trust has the highest Property Yield value of 5.54%, followed by Mapletree Commercial Trust and Suntec REIT. .
  • Property Portfolio Value: The former Capitaland Mall Trust has the highest AUM value by a considerable margin even before the merger, at $11.5B.

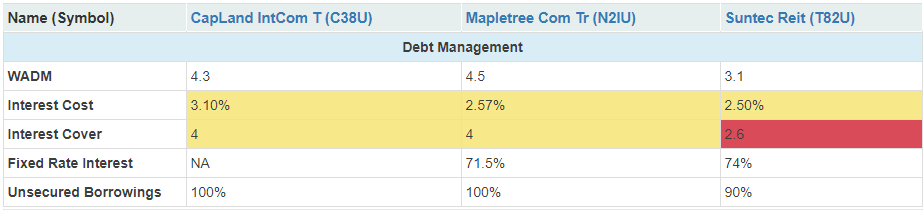
Debt Management

Debt Management comparison between the 3 REITs. Information taken from the StocksCafe REIT screener. Values taken on 4th January 2021

The above table shows the corresponding lease management values of the 3 REITs. Note that for CICT, values for the former Capitaland Mall Trust are shown instead. Some observations that can be made are shown below:

  • Weighted Average Debt Maturity (WADM): Capitaland Integrated Commercial Trust and Mapletree Commercial Trust has higher WADM values, at 4.3 and 4.5 years respectively.
  • Interest Cost: All 3 REITs have Cost of Debt values ranging between 2.5% to 3.1%
  • Interest Coverage Ratio: Suntec REIT has a lower Interest Coverage Ratio compared to the other REITs, at 2.6x.
  • Unsecured Borrowings: Almost all the borrowings made by the 3 REITs are unsecured.

Kenny Loh is a Senior Consultant and REITs Specialist of Singapore’s top Independent Financial Advisor. He helps clients construct diversified portfolios consisting of different asset classes from REITs, Equities, Bonds, ETFs, Unit Trusts, Private Equity, Alternative Investments and Fixed Maturity Funds to achieve an optimal risk adjusted return. Kenny is also a CERTIFIED FINANCIAL PLANNER, SGX Academy REIT Trainer, Certified IBF Trainer of Associate REIT Investment Advisor (ARIA) and also an invited speaker of REITs Symposium and Invest Fair. Kenny Loh also offers REIT Portfolio Advisory for a fee. Do contact him at kennyloh@fapl.sg 

Continue ReadingIntegrated Retail/Office Development REITs: How do they compare?

Retail REITs in Singapore: How do they stack up?

  • Post author:

Retail REITs in Singapore have rebounded since Phase 2 in Singapore began. In this article, we will be covering 5 predominantly retail REITs in Singapore, namely Capitaland Integrated Commercial Trust, Frasers Centrepoint Trust, SPH Reit, Starhill Global REIT and Lendlease Global Commercial REIT, comparing their portfolio information, financial ratios, etc.

REIT Portfolio Overview

Capitaland Mall Trust recently merged with Capitaland Commercial Trust, to form Capitaland Integrated Commercial Trust. Owning 5 Retail/Office, 8 Office and 11 Retail Developments, wholly in Singapore, CICT is the largest market capitalisation trust in Singapore.


Frasers Centrepoint Trust owns 7 Retail Malls in Singapore, including the newly-renovated Northpoint City. Mostly located away from the downtown, these malls seek to serve housing estates.


SPH Reit owns 5 properties, all of which are Retail Malls. 3 of the malls, The Rail Mall, Clementi Mall and Paragon are situated in Singapore, while Figtree Grove Shopping Centre and Westfield Marion Shopping Centre are located in Australia.


Starhill Global REIT owns properties in China, Japan, Malaysia, Australia and Singapore. In Singapore, Starhill Global REIT owns 2 properties, namely Ngee Ann City and Wisma Atria, which make up 70.1% of its total asset value.


Lendlease Global Commercial REIT owns 2 properties, 313 Somerset in Singapore and Sky Complex, a freehold office complex in Milan, Italy, with 313 Somerset having 71.5% of the IPO Portfolio. Lendlease Global Commercial REIT has also recently acquired a 5% stake in Jem, a shopping mall in Jurong East, Singapore.

Portfolio Distribution

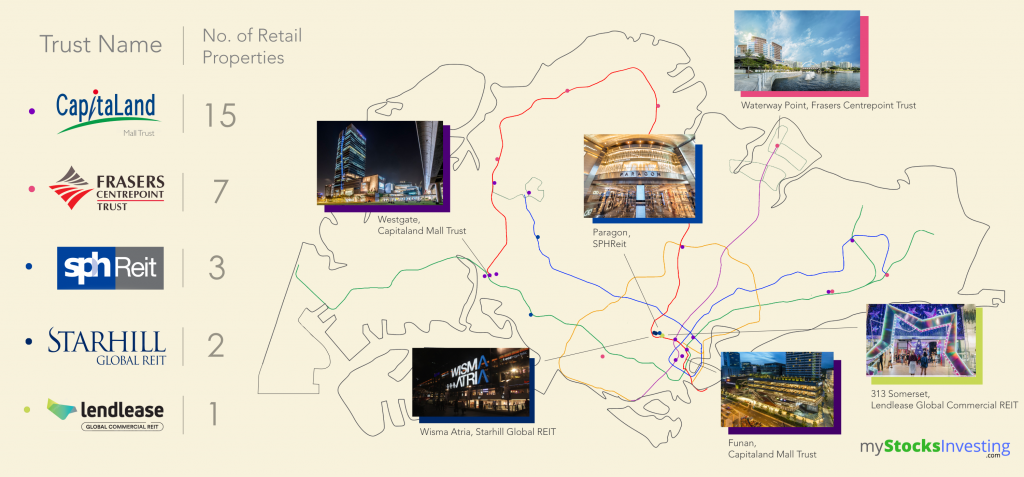
Singapore geographical distribution of REIT retail malls. Note: This diagram shows the properties of Capitaland Mall Trust before their merger, and Frasers Centrepoint Trust before acquisition.

The above diagram shows the geographical distribution of each REIT’s retail properties. Some observations that can be drawn out include:

  • Capitaland Integrated Commercial Trust-owned retail malls (formerly Capitaland Mall Trust before the merger) can be found throughout Singapore, in both housing estates (e.g Junction 8) and downtown areas (e.g Plaza Singapura).
  • Frasers Centrepoint Trust-owned retail malls are mostly found in housing estates away from the downtown areas.
  • Both Starhill Global REIT and Lendlease Global Commercial REIT’s Singapore portfolio own retail malls in Orchard Road. 
  • SPH Reit owns 3 retail malls in Singapore, 2 in housing estates in the west, and Paragon at Orchard Road.

Fundamental Ratios

Fundamental Ratio comparison between the 5 REITs. Information taken from the StocksCafe REIT screener. Values taken on 8 November 2020

The above table shows the corresponding fundamental ratios of the 5 REITs. Some observations that can be made are shown below:

  • Yield (ttm): At current prices, all 5 REITs except Starhill Global REIT have relatively low yields of below 5%. However, yield (ttm) is not a meaningful unit of measurement at the moment, due to recent dividend cuts due to the pandemic, and the switching of dividend payouts of some REITs to a semi-annual payout schedule (e.g Starhill Global REIT).
  • Gearing: Other than SPHReit (with a low gearing ratio of 30.5%) and Starhill Global REIT (with a higher than average gearing ratio of 39.7%), the other 3 REITs have gearing ratios around 35%.
  • Starhill Global REIT and Lendlease Global Commercial REIT are currently relatively undervalued with Price/NAV values of 0.527 and 0.753 respectively. compared to the other 3 REITs.

Lease Management

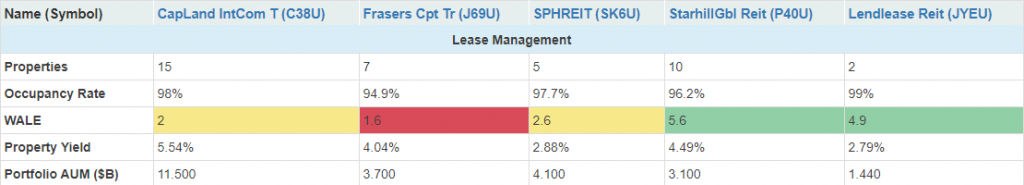
Lease Management comparison between the 5 REITs. Information taken from the StocksCafe REIT screener. Values taken on 8 November 2020

The above table shows the corresponding lease management values of the 5 REITs. Note that for CICT, values for the former Capitaland Mall Trust are shown instead. Some observations that can be made are shown below:

  • No. of Properties: Capitaland Integrated Commercial Trust owns the most properties, with 16 being Integrated Developments/Retail Properties. Both Frasers Cpt Trust and SPHReit are wholly Retail REITs, while the rest include offices in their portfolios.
  • Occupancy Rate: All 5 REITs have strong occupancy rates of above 94%, with the lowest being Frasers Cpt Trust at 94.9%.
  • Weighted Average Lease Expiry (WALE): Starhill Global REIT and Lendlease Global Commercial REIT have the highest WALE values, at around 5 years. The remaining 3 REITs have lower WALE values, ranging between 1.6 years to 2.6 years.
  • Property Yield: Capitaland Integrated Commercial Trust, Frasers Cpt Trust and Starhill Global REIT have Property Yield values of between  4-6%, while the remaining 2 REITS have values of about 2.8%.
  • Property Portfolio Value: The former Capitaland Mall Trust has the highest AUM value by a considerable margin even before the merger, at $11.5B.

Debt Management

Debt Management comparison between the 5 REITs. Information taken from the StocksCafe REIT screener. Values taken on 8 November 2020

The above table shows the corresponding lease management values of the 5 REITs. Note that for CICT, values for the former Capitaland Mall Trust are shown instead. Some observations that can be made are shown below:

  • Weighted Average Debt Maturity (WADM): Capitaland Integrated Commercial Trust has the highest WADM value, at 4.3 years.
  • Interest Cost: Lendlease Global Commercial REIT has the lowest Interest Cost, at 0.86%. The other REITs have higher Cost of Debt values, ranging between 2.4% to 3.23%
  • Interest Coverage Ratio: Lendlease Global Commercial REIT has a considerably higher Interest Coverage Ratio compared to the other REITs, at 9.2x.
  • Unsecured Borrowings: SPHReit is the only REIT in this comparison that has 100% secured borrowings.

Kenny Loh is a Senior Consultant and REITs Specialist of Singapore’s top Independent Financial Advisor. He helps clients construct diversified portfolios consisting of different asset classes from REITs, Equities, Bonds, ETFs, Unit Trusts, Private Equity, Alternative Investments and Fixed Maturity Funds to achieve an optimal risk adjusted return. Kenny is also a CERTIFIED FINANCIAL PLANNER, SGX Academy REIT Trainer, Certified IBF Trainer of Associate REIT Investment Advisor (ARIA) and also an invited speaker of REITs Symposium and Invest Fair. Kenny Loh also offers REIT Portfolio Advisory for a fee. Do contact him at kennyloh@fapl.sg 

Continue ReadingRetail REITs in Singapore: How do they stack up?