Learn different ways to protect your assets and avoid distributing them to the wrong people.
Join us to gain valuable insights into estate planning and take the first step towards effectively guarding your wealth. No prior knowledge is required, and all are welcome.
📅 Date: Saturday, 24 Oct 2026 🕑 Time: 10:00 AM – 12:00 PM 📍 Venue: Ocean Financial Centre, #26-01
Kenny Loh CFP® AEPP® IBFA MBA is a Certified Estate Planner specializing holistic estate and legacy planning. He empowers clients to build sustainable passive income and robust “Safety Net” structures—integrating Wills, LPAs, and Trusts—to protect wealth and ensure a seamless legacy across all life stages.
Michelle:“Let’s take the temperature of the S-REIT market first. Where are we now—and who have been the clear winners and losers to date?”
Kenny:
“Michelle, if we look strictly at share prices since the start of 2026, the honest answer is: there are virtually no winners. Persistent rate uncertainty has kept equity valuations pinned down across the entire board. FTSE ST REIT Index has dropped from 2026 high of 725 to 633 as of yesterday close. (12.6% YTD declines)
However, beneath those flat share price charts, we are seeing a major operational divergence in earnings and DPU.
The outperforming side of this ‘K-shape’ belongs to REITs delivering genuine DPU expansion—like CapitaLand Integrated Commercial Trust (CICT), Keppel DC REIT, Lendlease Global Commercial REIT, Alpha Integrated REIT. They’re benefiting from lower domestic SORA rates compared to peak years, active portfolio restructuring, and strong local rental reversions.
On the losing end, you have offshore commercial assets—especially US office REITs—and highly leveraged small-caps suffering structural DPU cuts from sticky overseas borrowing costs and persistent vacancy risks.”
Michelle:“REIT investors have endured several difficult years. Is the pain still mainly an interest-rate story, or are we now seeing a much bigger divide between REITs with genuinely strong assets and balance sheets and those with structural problems?”
Kenny:
“It was an interest-rate story, but now it’s purely a fundamental story.
When rates spiked, the rising tide dragged all ships down together. But now that rates have plateaued for a while, the tide is out (the REIT Managers have sufficient time to make adjustment to their portfolio and optimise the capital structure)—and we can clearly see who’s been swimming without shorts.
The divide comes down to two things: aggregate leverage and rental reversions. The strong blue-chips kept debt hedges above 70%, maintained leverage below 40%, and can push through positive rental growth to offset elevated debt costs. The weaker, un-hedged REITs with >40% gearing are forced to absorb negative reversions while paying steep interest expenses. Rate cuts alone won’t fix a broken asset structure.”
Michelle:“For investors sitting on sizeable losses, what’s the decision framework now: hold and collect distributions, average down, or admit the original thesis changed and get out?”
Kenny:
“I break it down into three clear rules for my clients:
First, Hold and Collect if the operational thesis is intact—meaning positive rental reversions, covered distributions, and a manageable debt expiry profile. You’re being paid to wait.
Second, Average Downonly on high-quality operational winners whose stock prices were dragged down by macro sentiment, rather than broken business models.
Third, Cut Losses if you see structural DPU erosion, gearing creeping past 42–45% without a clear recapitalization plan, or fundamental sector decay like secondary US office space. Don’t let price anchoring trap your money when higher-yielding, lower-risk opportunities exist elsewhere.”
Michelle:“Where would you actually be prepared to average down today? Which S-REIT segments give you the best combination of sustainable yield and potential capital upside?”
Kenny:
“I would comfortably average down in Suburban Retail, Logistics, and select Data Centres.
Suburban retail hubs like Frasers Centrepoint Trust or CICT enjoy sticky essential consumer spending and tight supply. Industrial and logistics REITs continue to capture supply chain shifts across Southeast Asia.
My strict rule for averaging down: look for strong sponsor backing, low aggregate leverage (ideally under 40%), active capital recycling, and proven DPU resilience.”
Michelle:“And where would you not average down, however attractive the headline yield looks? What tells you a 6% or 7% yielding REIT is actually a value trap?”
Kenny:
“When an S-REIT trades at an 8% to 11% headline yield, the market isn’t giving you a bargain—it’s pricing in a dividend cut, an asset write-down, or a rights issue.
The ultimate red flags for a value trap are:1. A ‘refinancing wall’ where a massive block of debt matures within 12 months at much higher rates.2. Interest Coverage Ratios (ICR) dropping close to MAS’s regulatory threshold of 1.5x.3. Persistent negative rental reversions year after year.”
Michelle:“If you’re tired of waiting for S-REITs to recover but still want income, what competes most convincingly for that money today—banks, bonds, income ETFs, or something else?”
Kenny:
“Singapore Banks—DBS, OCBC, UOB—remain the most direct competitor. They offer strong dividend yields backed by robust capital ratios and excess capital management.However current valuation is stretched for these banks (DBS 3.1x PB with 3.2% yield, OCBC 2.3x with 2.6% yield)
Beyond equities, S$ IG corporate bonds (3-5%), private credit (7-10%), and high-dividend yield ETFs give investors steady 5% to 6% yields without single-stock volatility. REITs still belong in an income portfolio, but today’s market demands a barbell strategy alongside fixed income and high-dividend equities.”
Michelle:“One argument for staying with REITs is that you’re being paid while you wait. But after years of weak capital performance, should investors pay much more attention to total return rather than distribution yield?”
Kenny:
“100%, Michelle. Yield without capital preservation is an illusion. A 7% yield means nothing if the underlying Net Asset Value (NAV) drops 10% every year.
Total return is Distribution Yield plus NAV growth. Investors must look past headline yield and choose REIT managers who create value through Asset Enhancement Initiatives (AEIs) and selling non-core properties above book value to pay down debt.”
Michelle:“What about the rate cycle? Are we at the point where a good REIT should be able to perform without needing interest rates to fall dramatically?”
Kenny:
“Absolutely. A high-quality REIT should never rely on a central bank bailout to survive.
The best managers have already adapted to this ‘higher-for-longer’ baseline. They’re running high occupancy rates above 95%, generating organic rent growth of 5% to 10%, and recycling non-core assets to keep their cost of debt low. Lower rates will be a welcome bonus, but the true winners are already performing today.”
Michelle:“There’s also been huge enthusiasm around data centres because of AI demand. Are data-centre REITs genuinely a way for income investors to participate in the AI boom, or are investors paying too much for that narrative?”
Kenny:
“It is a genuine structural tailwind, but retail investors need to look past the hype.
AI expansion requires massive power capacity and hyperscale facilities, which benefits names with deep pockets. But data centres carry huge capital expenditure costs, rapid tech obsolescence, and power grid constraints.
Data centre REITs are a solid growth sleeve for an income portfolio, but you must evaluate power capacity rights and tenant creditworthiness rather than buying blindly into the ‘AI’ label.”
Kenny Loh is a distinguished Wealth Advisory Director with a specialization in holistic investment planning and estate management. He excels in assisting clients to grow their investment capital and establish passive income streams for retirement. Kenny also facilitates tax-efficient portfolio transfers to beneficiaries, ensuring tax-efficient capital appreciation through risk mitigation approaches and optimized wealth transfer through strategic asset structuring.
In addition to his advisory role, Kenny is an esteemed SGX Academy trainer specializing in S-REIT investing and regularly shares his insights on MoneyFM 89.3. He holds the titles of Certified Estate & Legacy Planning Consultant and CERTIFIED FINANCIAL PLANNER (CFP).
With over a decade of experience in holistic estate planning, Kenny employs a unique “3-in-1 Will, LPA, and Standby Trust” solution to address clients’ social considerations, legal obligations, emotional needs, and family harmony. He holds double master’s degrees in Business Administration and Electrical Engineering, and is an Associate Estate Planning Practitioner (AEPP), a designation jointly awarded by The Society of Will Writers & Estate Planning Practitioners (SWWEPP) of the United Kingdom and Estate Planning Practitioner Limited (EPPL), the accreditation body for Asia.
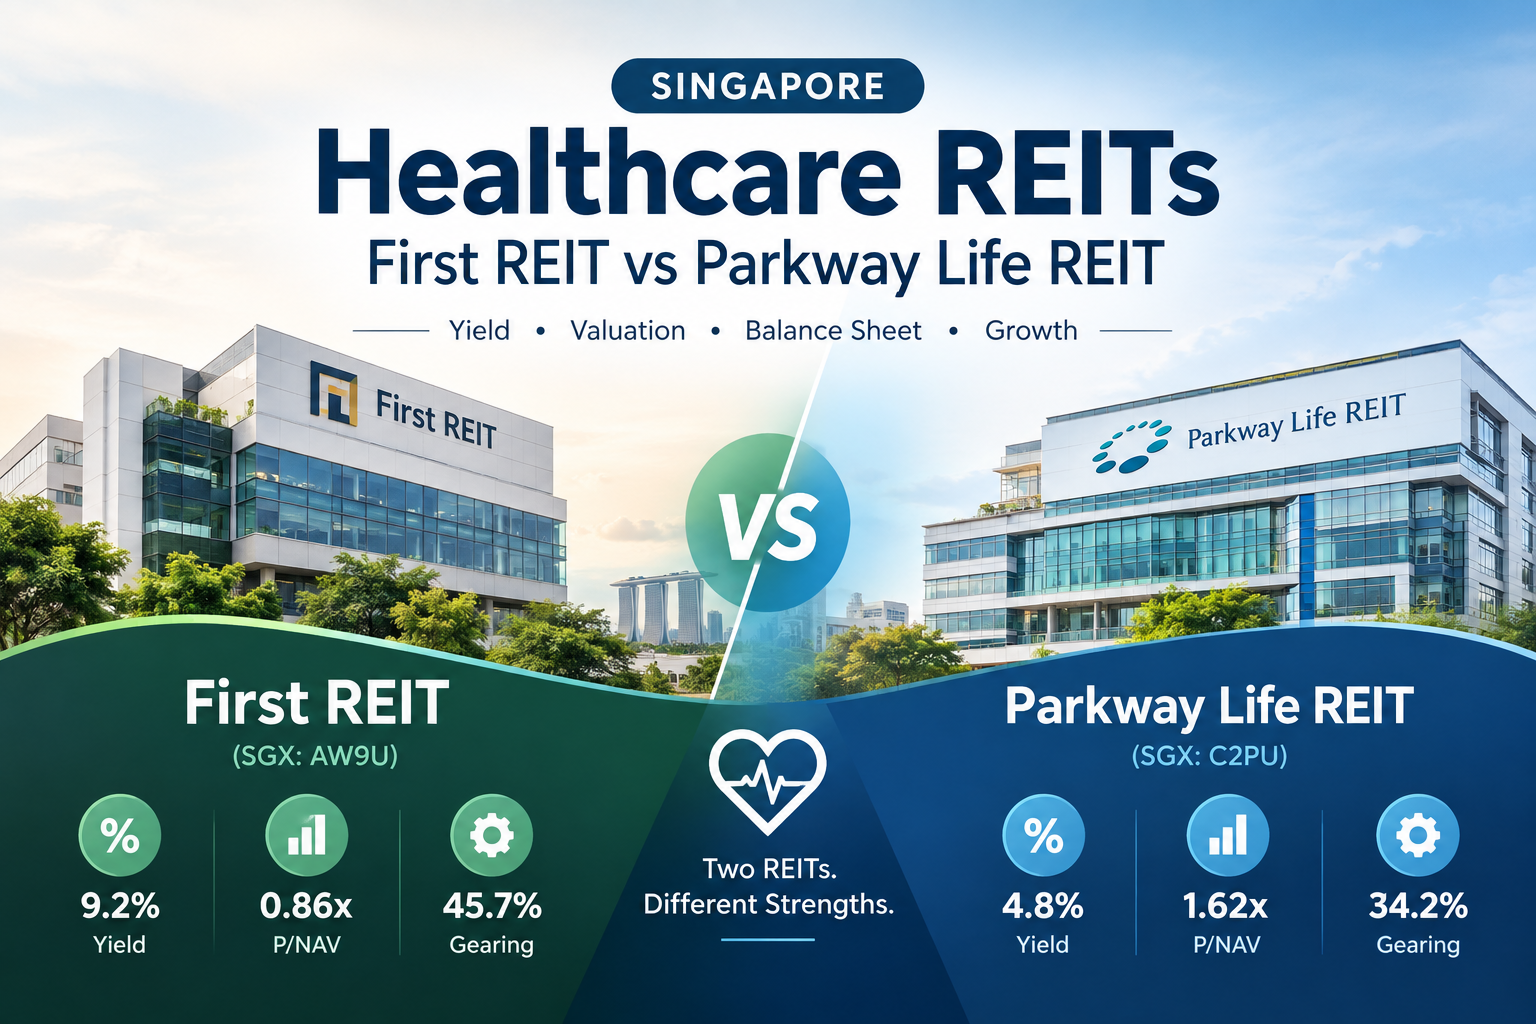
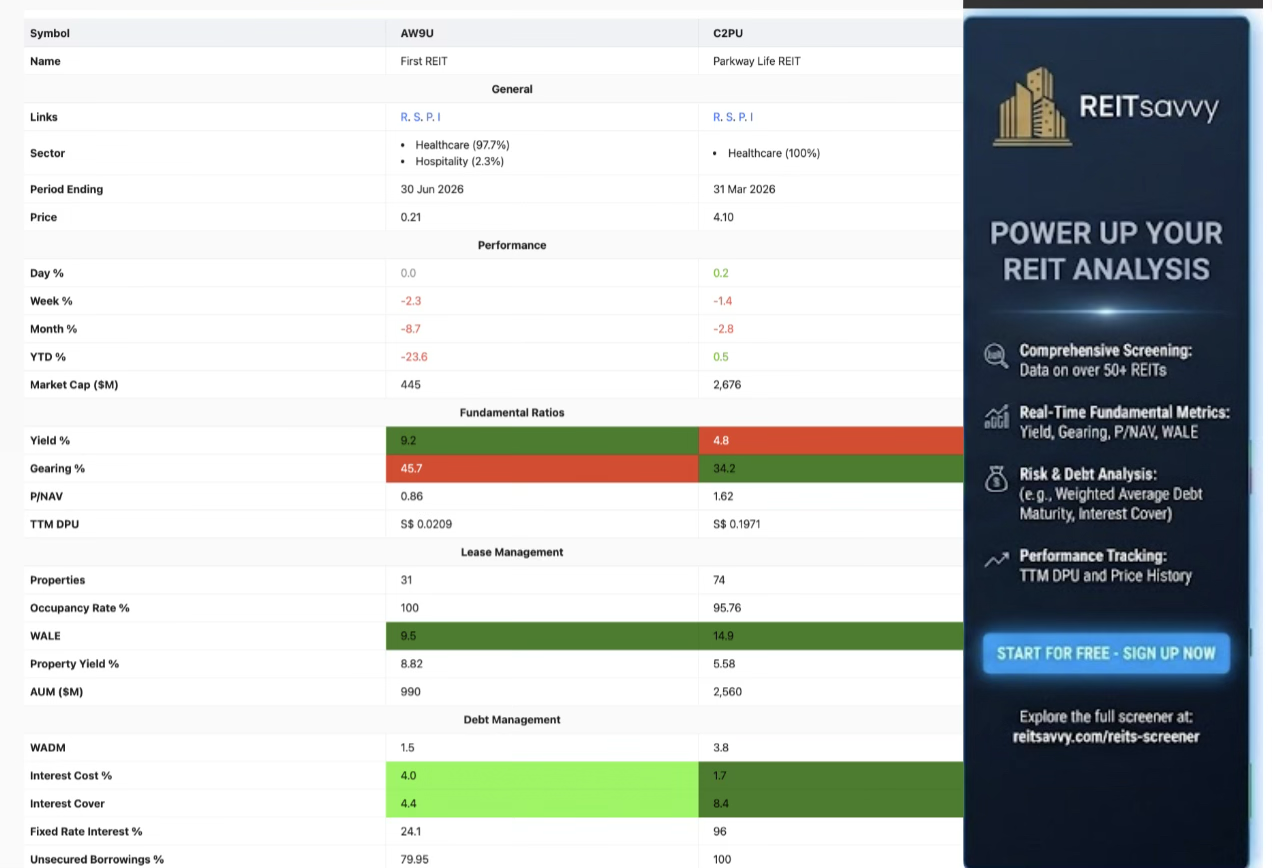
Singapore’s healthcare REIT segment provides investors with exposure to healthcare-related properties, with both First REIT and Parkway Life REIT showing a strong focus on the healthcare sector. Based on the comparison data, First REIT derives 97.7% of its portfolio from healthcare, with the remaining 2.3% in hospitality, while Parkway Life REIT has 100% healthcare exposure.
However, the two REITs present very different investment profiles. First REIT offers a significantly higher yield and trades below NAV, while Parkway Life REIT has lower gearing and stronger year-to-date performance but trades at a substantial premium to NAV. This creates a clear contrast between a higher-yield, value-oriented profile and a more conservatively valued healthcare REIT.
1. First REIT (SGX: AW9U) — The High-Yield Value Play
First REIT stands out for its combination of a high distribution yield and discounted valuation. At 9.2% yield and 0.86x P/NAV, it offers considerably more income and a lower valuation compared with Parkway Life REIT.
• Tailwinds:
Attractive Distribution Yield:First REIT’s 9.2% yield is almost twice Parkway Life REIT’s 4.8%. This makes it particularly attractive for investors who prioritise income generation.
Discount to NAV:With a P/NAV of 0.86, First REIT trades below its net asset value. This provides a potentially attractive valuation compared with Parkway Life REIT, which trades at 1.62x P/NAV.
Strong Healthcare Focus:Healthcare accounts for 97.7% of First REIT’s portfolio, meaning the REIT remains heavily positioned within the healthcare sector.
Positive Exposure to Healthcare While Maintaining Some Diversification:The remaining 2.3% hospitality exposure provides a small degree of diversification beyond healthcare, although the portfolio remains predominantly healthcare-focused.
• Headwinds:
High Gearing:First REIT’s gearing of 45.7% is considerably higher than Parkway Life REIT’s 34.2%. This indicates a more highly leveraged balance sheet and potentially less financial flexibility.
Weak Year-to-Date Performance:First REIT recorded a -23.6% YTD performance, significantly underperforming Parkway Life REIT’s +0.5%. This suggests that investor sentiment toward First REIT has been considerably weaker over the period shown.
Significant Valuation Discount:Although the 0.86x P/NAV can be viewed as a value opportunity, the discount also indicates that investors are placing a lower valuation on First REIT’s assets compared with Parkway Life REIT.
Lower Market Capitalisation:With a market capitalisation of S$445 million, First REIT is substantially smaller than Parkway Life REIT at S$2.676 billion. This gives the two REITs very different market profiles, with First REIT being the smaller counter.
2. Parkway Life REIT (SGX: C2PU) — The Lower-Gearing Healthcare Play
Parkway Life REIT presents a more conservative profile compared with First REIT. The REIT has 100% healthcare exposure, lower gearing of 34.2%, and positive YTD performance of 0.5%. However, investors are paying a substantial premium for this profile, with a P/NAV of 1.62x and a lower yield of 4.8%.
• Tailwinds:
100% Healthcare Exposure:Unlike First REIT, Parkway Life REIT’s portfolio is 100% healthcare, providing investors with direct exposure to the healthcare sector.
Lower Gearing:Parkway Life REIT’s gearing of 34.2% is significantly lower than First REIT’s 45.7%. This provides a comparatively stronger balance-sheet position based on the data shown.
Positive YTD Performance:Parkway Life REIT recorded a +0.5% YTD performance, compared with First REIT’s -23.6%. This indicates substantially stronger share-price performance over the period shown.
Larger Market Capitalisation:At S$2.676 billion, Parkway Life REIT has a market capitalisation more than six times that of First REIT. Its larger size distinguishes it from First REIT within the healthcare REIT comparison.
• Headwinds:
Lower Distribution Yield:Parkway Life REIT’s 4.8% yield is significantly lower than First REIT’s 9.2%. For investors focused primarily on income, this makes Parkway Life REIT less attractive on headline yield.
Premium to NAV:With a P/NAV of 1.62x, Parkway Life REIT trades significantly above its NAV. This contrasts sharply with First REIT’s 0.86x and means investors are paying a substantial premium for Parkway Life REIT.
Less Attractive Valuation Compared with First REIT:While Parkway Life REIT has stronger YTD performance and lower gearing, its higher P/NAV and lower yield make it less compelling for investors specifically seeking discounted valuations and higher income.
Recent Performance Remains Modest:Although Parkway Life REIT outperformed First REIT on a YTD basis, its displayed YTD gain of 0.5% remains relatively modest compared with the significant valuation premium reflected in its 1.62x P/NAV.
POWER UP YOUR REIT ANALYSIS
Comprehensive Screening: Data on over 30+ Singapore REITs
Real-Time Fundamental Metrics: Yield, Gearing, P/NAV, WALE
Kenny Loh is a distinguished Wealth Advisory Director with a specialization in holistic investment planning and estate management. He excels in assisting clients to grow their investment capital and establish passive income streams for retirement. Kenny also facilitates tax-efficient portfolio transfers to beneficiaries, ensuring tax-efficient capital appreciation through risk mitigation approaches and optimized wealth transfer through strategic asset structuring.
In addition to his advisory role, Kenny is an esteemed SGX Academy trainer specializing in S-REIT investing and regularly shares his insights on MoneyFM 89.3. He holds the titles of Certified Estate & Legacy Planning Consultant and CERTIFIED FINANCIAL PLANNER (CFP).
With over a decade of experience in holistic estate planning, Kenny employs a unique “3-in-1 Will, LPA, and Standby Trust” solution to address clients’ social considerations, legal obligations, emotional needs, and family harmony. He holds double master’s degrees in Business Administration and Electrical Engineering, and is an Associate Estate Planning Practitioner (AEPP), a designation jointly awarded by The Society of Will Writers & Estate Planning Practitioners (SWWEPP) of the United Kingdom and Estate Planning Practitioner Limited (EPPL), the accreditation body for Asia.